

Tidewater currently trades at $80.85 per share and has shown little upside over the past six months, posting a small loss of 1.3%. The stock also fell short of the S&P 500’s 21.1% gain during that period.
Is now the time to buy TDW? Find out in our full research report, it’s free.
Why Is TDW a Good Business?
Operating one of the world's largest fleets with over 200 vessels spanning 30 countries, Tidewater (NYSE:TDW) operates offshore service vessels that transport supplies, equipment, and workers to oil rigs and platforms.
1. Skyrocketing Revenue Shows Strong Momentum
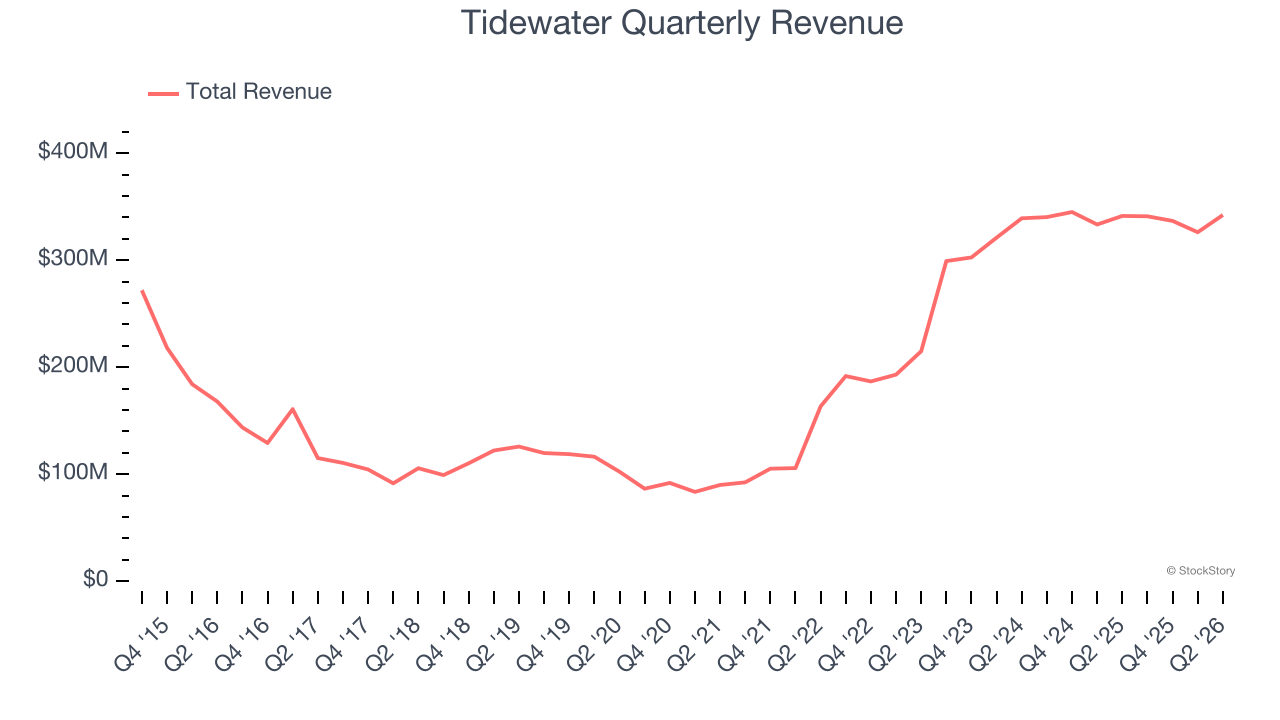
Cyclical industries such as Energy can make mediocre companies look great for a time, but a long-term view reveals which businesses can actually withstand and adapt to changing conditions. Luckily, Tidewater’s sales grew at an incredible 30.8% compounded annual growth rate over the last five years. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
2. EBITDA Margin Rising, Profits Up
Adjusted EBITDA margin is an important measure of profitability for the sector and accounts for the gross margins and operating costs mentioned previously. Unlike operating margin, it is not distorted by accounting conventions around reserves, drilling costs, and assumptions on commodity consumption from the well or basin. Adjusted EBITDA highlights the economic reality of how much cash the rock produces before the capital structure (debt service) and the drilling budget (capex) are considered.
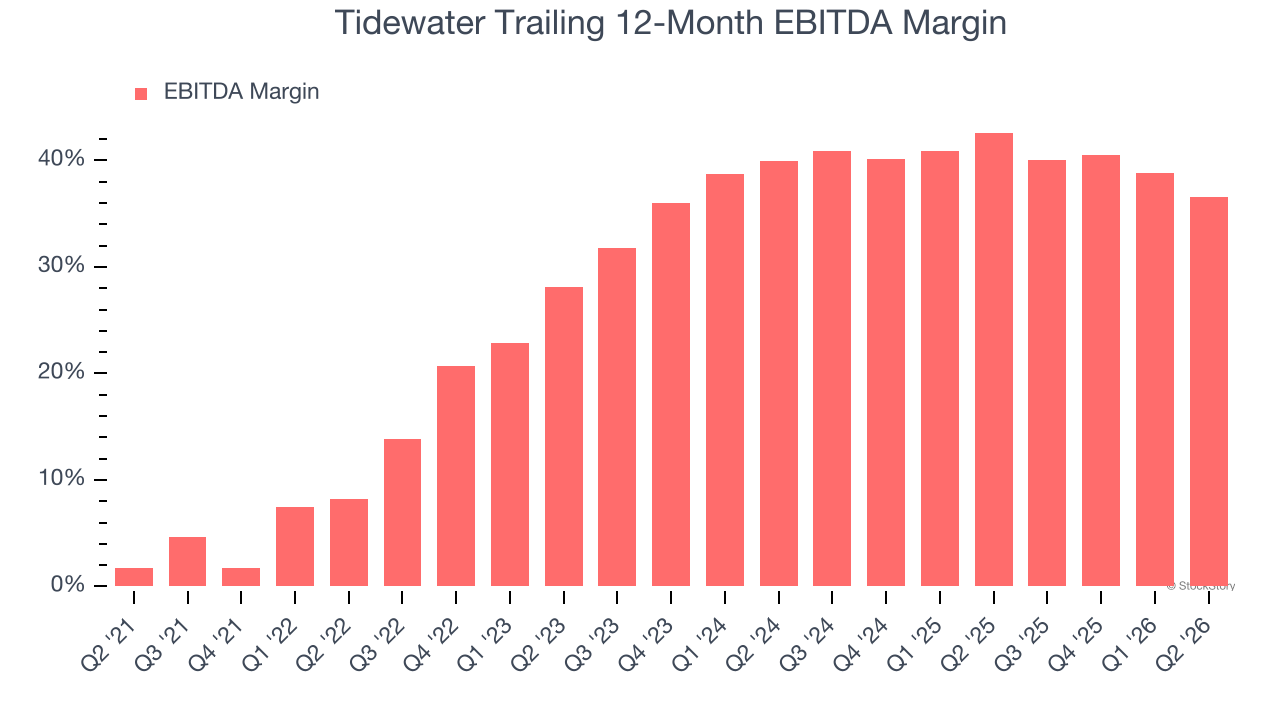
Looking at the trend in its profitability, Tidewater’s EBITDA margin rose by 28.4 percentage points over the last year, as its sales growth gave it immense operating leverage. Its EBITDA margin for the trailing 12 months was 36.6%.
3. Excellent Free Cash Flow Margin Boosts Reinvestment Potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
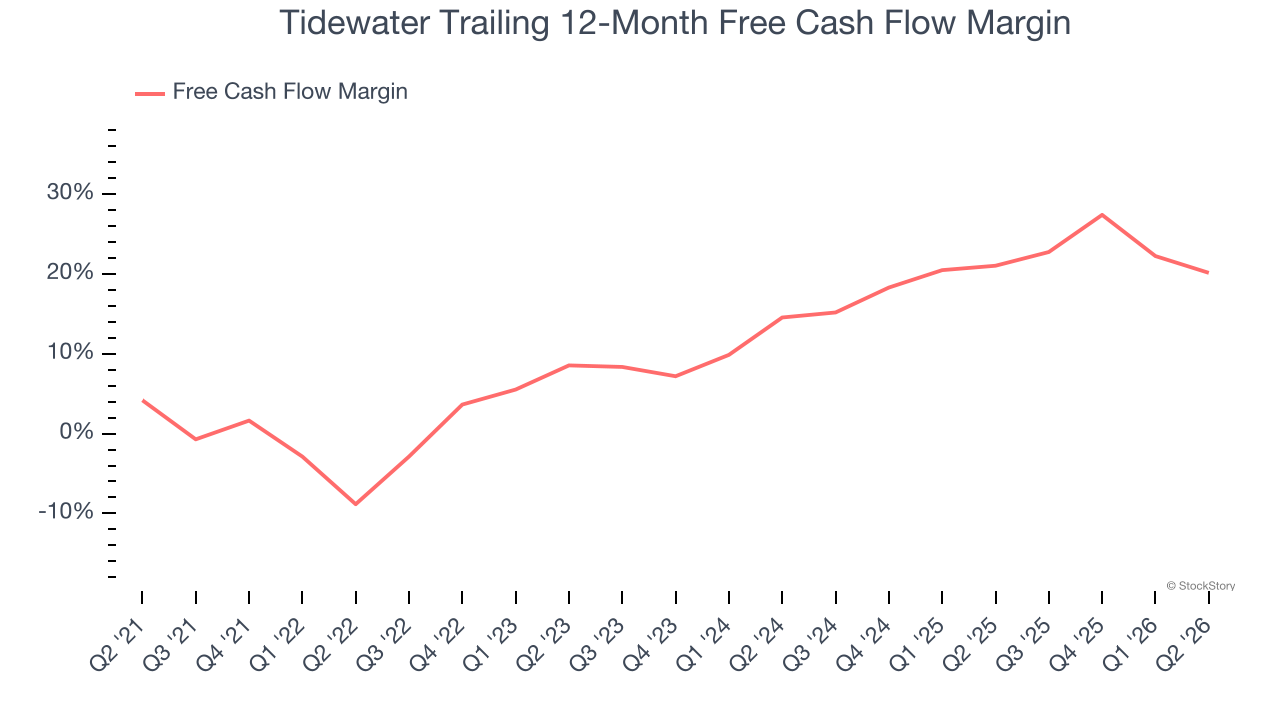
Tidewater has shown robust cash profitability, giving it an edge over its competitors and the ability to reinvest or return capital to investors. The company’s free cash flow margin averaged 14.7% over the last five years, quite impressive for an upstream and integrated energy business.
Final Judgment
These are just a few reasons why Tidewater ranks highly on our list. With its shares trailing the market in recent months, the stock trades at 15.7× forward P/E (or $80.85 per share). Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.